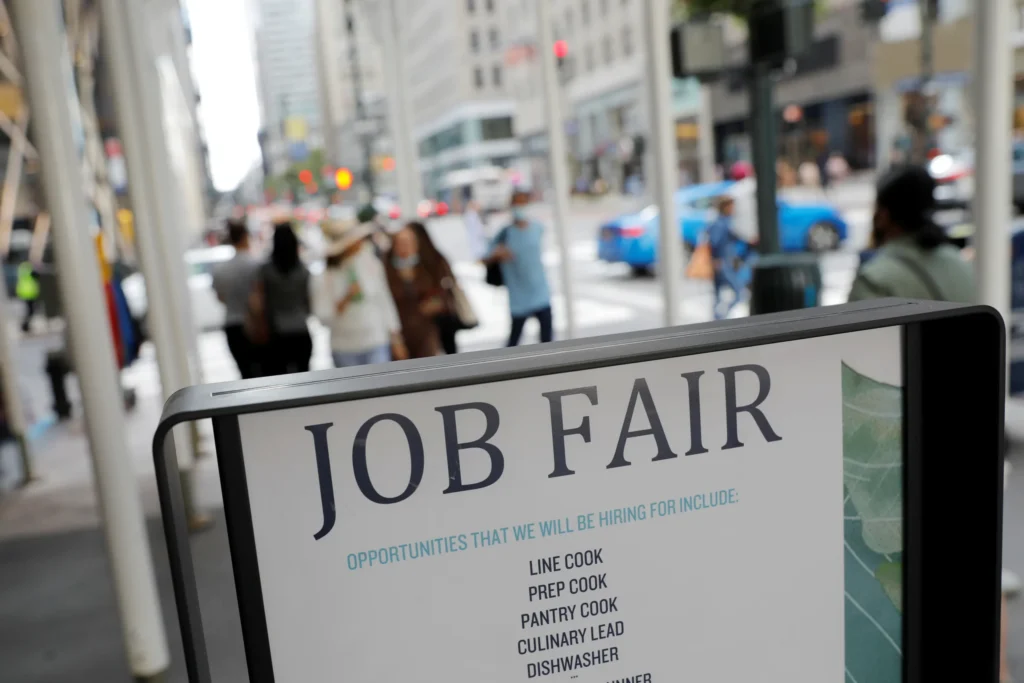
The number of Americans filing new claims for unemployment benefits saw an unexpected decline last week, a trend that, while potentially influenced by the Labor Day holiday, underscores the continued stability of the U.S. labor market. This resilience provides the Federal Reserve with a crucial buffer as it navigates the persistent challenge of inflation, exacerbated by geopolitical tensions in the Middle East. In a move that signals its commitment to price stability, the central bank recently raised interest rates for the first time since July 2023 and indicated further borrowing cost hikes are on the horizon.
Economists widely view the latest figures as indicative of a labor market that has regained its footing after a period of summer uncertainty. Samuel Tombs, Chief U.S. Economist at Pantheon Macroeconomics, commented, "The exceptionally depressed number last week might reflect seasonal adjustment issues related to Labor Day, but the underlying picture remains encouraging. For now, then, the Fed will remain laser-focused on inflation." This sentiment highlights the prevailing economic narrative: a robust labor market allows the Fed to prioritize its inflation-fighting mandate without immediate concerns of triggering widespread job losses.
Labor Market Snapshot: Initial Claims and Trends
According to the Labor Department’s report on Thursday, initial claims for state unemployment benefits fell by 10,000 to a seasonally adjusted 196,000 for the week ending September 12. This figure represents the lowest level recorded since mid-July, surpassing the forecast of 208,000 claims by economists polled by Reuters.
The sharp decrease is largely attributed to statistical anomalies surrounding the Labor Day holiday, which occurred on Monday, September 1st. Seasonal adjustments for unemployment claims around public holidays are notoriously complex and can lead to week-to-week volatility. To provide a clearer picture of underlying trends, analysts often refer to the four-week moving average of claims. This metric, designed to smooth out short-term fluctuations, also showed a positive trajectory, falling by 2,750 to 203,250 last week.
The period covered by this unemployment claims data is particularly significant as it aligns with the government’s survey of employers for the nonfarm payrolls component of the September employment report. The relative stability in the four-week average of claims between the August and September survey weeks suggests that overall labor market conditions have remained consistent. This consistency is crucial for understanding the broader employment landscape, as it indicates that the underlying pace of hiring and layoffs has not undergone significant shifts.
Broader Economic Context and Federal Reserve Actions
The steady state of the labor market has been a key talking point for Federal Reserve officials. Fed Chairman Kevin Warsh, in a previous statement, had characterized the labor market as "one basic sign of strength," asserting that policymakers believed "that the unemployment rate is basically running consistent with full employment." This assessment underpins the Fed’s confidence in its current monetary policy stance.
On Wednesday, the Federal Reserve implemented a widely anticipated 25-basis-point increase in its benchmark interest rate, pushing the federal funds rate target to the 3.75%-4.00% range. This marks the first rate hike since July 2023, signaling a renewed push to curb inflation. Fed officials have signaled their intention to continue raising borrowing costs in the coming months, a strategy aimed at cooling demand and bringing inflation back to the Fed’s 2% target. The conflict in the Middle East, which has driven up oil prices and heightened inflationary concerns, has added a layer of complexity to the Fed’s decision-making process.
Continuing Claims and Hiring Proxies
Beyond initial claims, the number of individuals receiving unemployment benefits after their initial week of aid, known as continuing claims, also offers insights into the labor market. These figures serve as a proxy for hiring activity. The report indicated a substantial drop of 39,000 in continuing claims, bringing the seasonally adjusted total to 1.730 million for the week ended September 5. This level represents the lowest since January 2024, further reinforcing the narrative of a tight labor market.
However, economists cautioned that continuing claims may also have been affected by seasonal adjustment issues. Abiel Reinhart, an economist at JPMorgan, noted, "Continuing claims are at similar levels to May 2023, a time when the unemployment rate was only 3.6%. The pattern of residual seasonality in continuing claims is different than for initial claims, and continuing claims could edge higher again starting in late September." This observation suggests that while the current figures are strong, there might be some upward revision in subsequent weeks, although the overall trend is still perceived as robust.
Underlying Factors Influencing the Labor Market
The unemployment rate stood at 4.1% in August, a figure that is being influenced by a confluence of factors. Low layoff rates remain a significant contributor, alongside a contracting labor force. This contraction is partly due to slower population growth, an increasing number of retirements, and stricter immigration policies. These demographic and policy shifts are contributing to a more constrained labor supply, which in turn supports higher employment levels and wage growth, even as businesses face economic headwinds.
Economists point to a general hesitancy among businesses to significantly expand their hiring. This caution is driven by several factors, including the lingering uncertainty surrounding the U.S.-Israeli conflict with Iran, which has kept oil prices elevated and fueled inflation. The elevated cost of energy, coupled with broader inflationary pressures, creates a challenging operating environment for many companies.
Market Reactions and Financial Indicators
The financial markets reacted to the economic data with a degree of optimism. Stocks on Wall Street saw gains as investors found encouragement in a pullback in oil prices, though concerns about the potential for the Middle East conflict to widen persisted, keeping crude above the $100 a barrel mark. The U.S. dollar eased against a basket of major currencies, while U.S. Treasury yields fell. The yield on the benchmark 10-year Treasury note slid to approximately 4.947% after briefly breaching the 5.0% threshold earlier in the week, reflecting shifting investor sentiment and expectations about future interest rate hikes.
Housing Market Under Pressure from Rising Inflation and Rates
In stark contrast to the resilience of the labor market, the U.S. housing sector is facing significant headwinds, primarily driven by rising inflation and the consequent surge in mortgage rates. A separate report from the Commerce Department’s Census Bureau revealed a decline in permits for future single-family home construction. In August, these permits dropped by 1.8% to a seasonally adjusted annualized rate of 878,000 units. While this represents a month-over-month decrease, building permits were up 1.3% on a year-over-year basis, indicating a more nuanced picture.
This dip in permits followed closely on the heels of news earlier in the week that single-family homebuilder sentiment had fallen to a one-year low in September. The National Association of Home Builders attributed this decline in optimism to a dual challenge: escalating mortgage rates and worsening labor shortages. The latter is partly a consequence of a crackdown on immigration, which has reduced the availability of construction workers, and increased material costs stemming from import tariffs.
Mortgage Rates and Housing Starts
The average rate on a 30-year fixed-rate mortgage has surged by nearly 100 basis points since the onset of the Middle East conflict. In the latest week, this average rate stood at 6.95%, marking the highest level since January 2025, according to data from mortgage finance firm Freddie Mac. This sharp increase in borrowing costs is making homeownership less affordable for many Americans, thereby dampening demand.
Despite the overall weakness in permits, actual single-family homebuilding saw a notable increase of 7.6% in August, reaching a rate of 918,000 units. On a year-over-year basis, single-family housing starts rose by 5.2%. However, this positive development was tempered by a significant drop in multi-family homebuilding, which plunged by 22.5% to a rate of 344,000 units in August. Multi-family housing starts also decreased by 15.5% year-over-year.
The segment of building permits for housing projects with five units or more, known for its volatility, experienced a 3.1% decline, settling at a rate of 467,000 units last month. Cumulatively, overall building permits fell by 2.7% to a rate of 1.394 million units in August, though they were up 3.5% year-over-year. Overall housing starts across all residential categories decreased by 2.6% to a pace of 1.275 million units, marking a 1.2% decline compared to August of the previous year. This sustained contraction in residential investment, which has occurred in five of the last six quarters, underscores the challenging environment for the housing sector.
Existing Home Sales and Future Outlook
Adding to the mixed picture in the housing market, a third report from the National Association of Realtors indicated an increase in contracts to buy previously owned homes. These contracts rose by 0.3% in August. However, on a year-on-year basis, contracts saw a substantial decline of 4.7%, suggesting a cooling market for existing homes.
Carl Weinberg, Chief Economist at High Frequency Economics, offered a somber assessment of the housing sector’s prospects: "The housing market is not the brightest dot on the Fed’s radar right now, with multiple supply and price shocks hitting output and demand all at once. The Fed cannot fix what is wrong in this sector with monetary policy." This statement highlights the limitations of monetary policy in addressing the complex, supply-side issues and external price shocks that are currently impacting the housing market. The Fed’s tools are primarily designed to influence demand, and while they can indirectly affect housing through interest rates, they are less effective in resolving challenges related to labor shortages, material costs, and geopolitical instability.
The confluence of a resilient labor market and a beleaguered housing sector presents a complex economic landscape. While the Federal Reserve has room to maneuver on the inflation front due to strong employment, the persistent challenges in the housing market could have broader implications for consumer confidence and overall economic growth in the coming months. The ongoing geopolitical situation in the Middle East adds another layer of uncertainty, potentially impacting energy prices and global supply chains, further complicating the economic outlook.